TL;DR

Get the little things that make your day delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
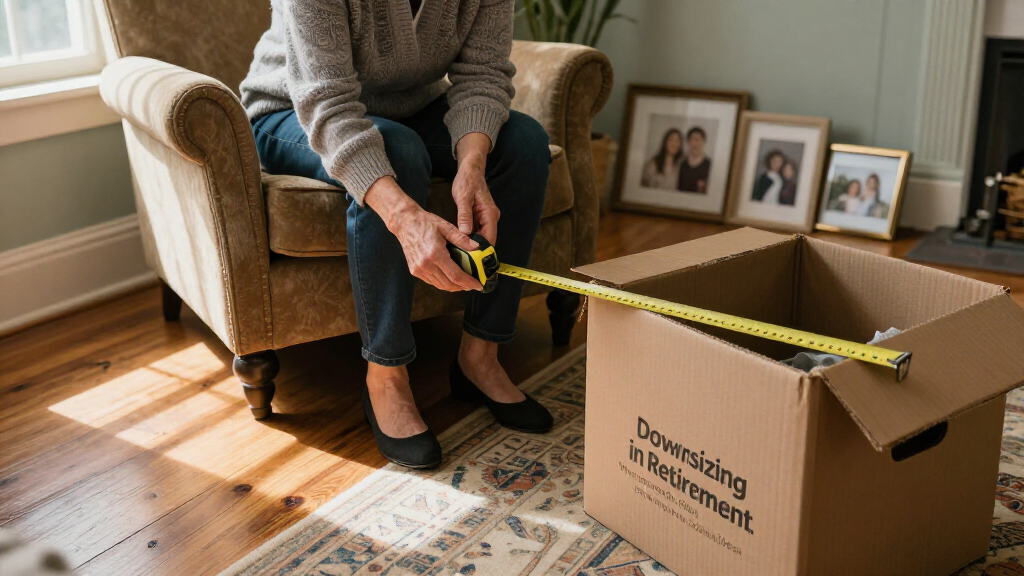
A LifeHack report argues that selling a retirement home and buying a smaller one does not automatically improve finances: sale, purchase and moving costs can consume much of the price difference. It recommends calculating how many years of housing savings would be needed to recover those costs, while weighing practical needs and personal ties alongside the numbers.
A LifeHack report on retirement downsizing says homeowners should calculate the move’s full costs and its expected annual savings before selling, because sale, purchase and moving expenses can absorb much of the price difference between homes. The report’s central point is that downsizing is not automatically a way to free up money: whether it pays depends on how long a retiree lives in the new home and how much cheaper it is to own.
The report frames a move as a payback calculation. Add the one-time costs of selling, buying and moving, then divide that total by the expected annual reduction in housing costs. The result is the number of years required for the savings to catch up with the expense. If the household moves again, or the expected savings do not materialize, the move may not reach that break-even point.
It cites Freddie Mac guidance that seller fees and taxes can run 2% to 4% of the sale price, separate from agent commissions, which the guide gives as a broad 3% to 8% range. Freddie Mac puts typical buyer closing costs at 2% to 5% of the purchase price. These are budgeting ranges, not quotes; the report notes that commissions are negotiable and actual expenses depend on the transaction.
Moving expenses add to the bill. LifeHack cites Move.org estimates of about $7,600 for a full-service local move under 100 miles and $9,140 or more for a longer-distance move. Its example compares selling a $450,000 home and purchasing a $300,000 one: the $150,000 difference in listed prices does not equal cash gained, because the report estimates transaction costs of roughly $28,500 to $69,000 before moving expenses or new furnishings and repairs.
The Move Needs a Real Payback
The calculation matters because the apparent equity released by selling is not the same as cash available after the move. Fees, closing costs, movers and costs of fitting out the new home reduce the amount left over. A retiree who expects the smaller home to improve monthly finances needs to compare the recurring expenses of both properties, not just their purchase prices.
The report also warns that savings can be modest when a current home is already paid off. It cites Harvard’s Joint Center for Housing Studies report, which found that in 2022, 59% of homeowners aged 65 to 79 and 69% of homeowners aged 80 and older had no mortgage. For those owners, a smaller property may reduce taxes, utilities or maintenance, but it may also add a condominium or homeowners association fee. The relevant figure is the net annual difference.
There are nonfinancial consequences, too. Proximity to family, familiar services, accessibility and the ability to host relatives can affect whether a move works. The report says a calculation cannot settle those preferences, but it can clarify what a household is paying for them.
Staying Is a Common Preference
Arguments for downsizing often focus on a larger home’s upkeep, stairs and unused rooms. LifeHack says that advice can overlook what a household would lose by leaving its neighborhood and routines, as well as the costs of acquiring and setting up another home. Its suggested approach is to treat the decision as both a housing plan and a financial one, rather than assuming that less space means lower total costs.
The report cites AARP’s 2024 Home and Community Preferences survey, in which 75% of adults aged 50 and older said they wanted to remain in their current home for as long as possible. That is a reported preference, not evidence that every respondent can stay or should do so. The figure does show why a financial case for moving should be weighed against a strong stated preference for remaining at home.
Cost estimates in the report are general ranges and its home-sale example is illustrative, not a forecast for any particular market. Individual outcomes depend on local prices, property condition, taxes, insurance, financing, moving distance and the terms agreed with agents and other providers.
“Downsizing is a life decision that sometimes pays. It is not a financial move that happens to change your life.”
— LifeHack report
Costs Depend on the Local Deal
The report does not provide a universal break-even period or a recommendation that applies to every retiree. Its example uses assumed sale and purchase prices, while its fee and moving figures are broad estimates. Actual transaction costs and annual savings remain unknown until a homeowner obtains specific estimates and compares the carrying costs of particular properties.
It is also unclear from the supplied material how long an individual household will remain in the new home, what unexpected repairs may arise, or how future taxes, insurance and association fees may change. Those factors can alter the payback calculation. The report’s cited survey and housing statistics describe defined populations and years, not the circumstances of every person considering a move.
Price Both Homes Before Deciding
The report’s practical next step is to build a household-specific estimate before listing a property. Owners can gather expected sale proceeds, agent and closing costs, moving quotes, purchase expenses and likely setup or repair costs. They can then compare annual taxes, insurance, utilities, maintenance and any association fees at the current and prospective homes.
Dividing the one-time costs by the estimated yearly savings gives a starting break-even point. Homeowners should also consider accessibility, support nearby and how long they expect to stay. No decision or timetable is provided in the source; the choice turns on the actual numbers and the household’s needs.
Key Questions
Does downsizing always save money in retirement?
No. A lower-priced home may reduce some expenses, but sale, purchase and moving costs can offset those savings. The report recommends comparing the total one-time cost with the expected annual reduction in housing expenses.
How do I calculate a break-even point?
Add the one-time costs of selling, buying, moving and setting up the new home. Divide that total by the estimated annual savings in housing costs. The result is an estimated number of years to recover the expense, assuming the savings continue.
What transaction costs does the report cite?
LifeHack cites Freddie Mac ranges of 2% to 4% of the sale price for seller fees and taxes, in addition to a broad 3% to 8% range for agent commissions, and 2% to 5% of the purchase price for buyer closing costs. These are estimates, not quotes, and actual terms vary.
Why might downsizing be less attractive if my home is paid off?
A mortgage-free owner has no mortgage payment to reduce. Moving may still lower taxes, utilities or maintenance, but those savings could be small relative to transaction costs, and a new property may add fees such as a condominium assessment.
What personal factors should I weigh alongside the math?
Consider accessibility, upkeep, proximity to family and services, familiar routines, and whether the new home can meet your needs over time. The report treats these as part of the decision, not as costs that can be captured fully in a financial estimate.
Source: rss
Products Worth Considering
As an affiliate, we earn on qualifying purchases.